ESG reporting has evolved from a regulatory requirement into a strategic imperative for businesses, and that shift puts it squarely on the board's agenda. As SAP's reporting guide frames it, organizations now recognize the value of transparent ESG disclosures in attracting investors, fostering trust, and mitigating risks. The practical consequence for directors is a two-part job: understand which reporting demands are legally mandatory and which are voluntary strategic choices, then set a coherent disclosure strategy rather than reacting piecemeal to fragmented demands.
ESG Reporting: A Strategic Imperative for Boards
ESG reporting summarizes the qualitative and quantitative benefits of a company's environmental, social, and governance activities. Because those disclosures let investors screen investments, align holdings to their values, and avoid companies exposed to environmental damage, social missteps, or corruption—as Wolters Kluwer's expert insights explain—the reports a company produces directly shape how capital markets judge it. That is why board oversight matters: the content, credibility, and consistency of ESG disclosures are now inputs to enterprise value, not back-office paperwork.
The financial stakes are concrete. An FSC overview of ESG for businesses cites an MSCI study finding that high-scoring ESG companies outperformed low-scoring peers on profitability, and notes Deloitte's reported finding that a 10-point higher ESG score correlated with a 1.2x higher enterprise value-to-EBITDA ratio. Those figures are secondary citations of third-party research, but they illustrate why investors treat ESG performance as a valuation question—and why boards should treat ESG reporting as a governance question.
From Compliance Burden to Value Creation: The Strategic Shift
The compliance mindset asks only: what must we disclose, and by when? The strategic mindset asks: what can disciplined disclosure do for the business? Boston College's Center for Corporate Citizenship notes that effective ESG reporting can enhance corporate reputation, build consumer confidence, and improve risk management, and that transparency helps stakeholders—including investors, customers, and regulators—assess a company's long-term value and commitment to responsible operations.
Reporting also works as an internal management tool. SAP's guide highlights that ESG reporting enables organizations to identify areas for improvement, set meaningful sustainability goals, and track progress over time. In other words, the same data infrastructure a company builds to satisfy disclosure demands can double as a performance-management system. For a board, that reframing changes the resource conversation: the question is not the minimum cost of compliance but the return on building reliable sustainability data, goal-setting, and tracking capability.
Navigating the Fragmented ESG Reporting Landscape: A Board's Framework
The landscape boards must navigate is genuinely fragmented. Wolters Kluwer's guidance is blunt: a universal standard does not yet exist, and ESG reporting instead takes the form of regional reporting frameworks, voluntary standards, and national legislation that vary significantly. FSC adds that compliance requirements are rapidly evolving as standard-setters respond to stakeholder concerns about vague or inflated sustainability claims.
For directors, the workable mental model is to sort every demand by its driver. Some disclosures are legally mandated by a regulator in a specific jurisdiction—these are non-negotiable and carry legal consequences. Others are voluntary adoptions of global standards, chosen to win credibility with particular audiences. The board's strategic task is to map each framework to the business driver it serves, so that mandatory work and voluntary choices reinforce rather than duplicate each other.
ESG Reporting Decision Framework for Boards
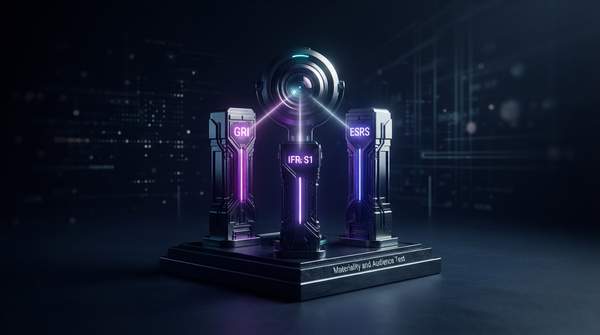
The matrix below categorizes the primary reporting drivers into mandatory requirements versus voluntary strategic choices, and maps the main frameworks and regulations to those drivers to clarify where board oversight attention belongs.
| Driver | Framework / Regulation | Purpose and Benefit | Scope |
|---|---|---|---|
| Mandatory compliance (regulatory mandate) | EU Corporate Sustainability Reporting Directive (CSRD); U.S. SEC climate disclosure rules | Legally required disclosure aimed at standardizing reporting for investor protection and market transparency | CSRD mandates detailed ESG disclosures for a broad range of companies, including non-EU companies with significant EU operations; SEC rules require U.S. public companies to disclose climate-related risks and greenhouse gas emissions in annual reports |
| Voluntary global baseline (investor information needs) | International Sustainability Standards Board (ISSB) standards | Global baseline for sustainability-related financial disclosures, harmonizing requirements across jurisdictions to avoid fragmented or conflicting approaches | Developing global baseline standards for sustainability-related financial disclosures |
| Voluntary global standard (stakeholder impact) | Global Reporting Initiative (GRI) | Standardized methodology for companies to disclose their ESG impacts, supporting credible and transparent stakeholder reporting | Voluntary; focused on a company's impacts on stakeholders |
| Climate-related financial disclosure | Task Force on Climate-related Financial Disclosures (TCFD) | Recommendations for reporting climate-related financial risks and opportunities across governance, strategy, risk management, and metrics | Voluntary recommendations; climate risks and opportunities |
| Strategic value creation | Effective ESG reporting practice | Enhances corporate reputation, builds consumer confidence, and improves risk management | Company-wide disclosure practice supporting stakeholder assessment of long-term value |
| Attracting investment | Transparent ESG disclosures | Lets investors screen investments, align to values, and avoid companies with environmental, social, or corruption risk | Investor-facing disclosures |
Reading the matrix as a decision tool: the first row defines the legal floor, and its scope determines which entities in a group structure must report. The middle rows are choices—ISSB-aligned disclosure serves investors assessing enterprise value, while GRI serves stakeholders assessing the company's impact on the world, and TCFD structures climate-specific risk disclosure. The final rows are the outcomes a board should expect a coherent strategy to produce: reputation, risk management, and investor confidence.
Strategic Oversight: Guiding Your Board's ESG Journey
Boards should proactively integrate ESG reporting into their strategic planning, moving beyond mere compliance to leverage it for long-term value creation and risk management. This is a strategic guide for directors, not a technical implementation manual for compliance teams, and it is not legal advice or a definitive interpretation of any regulation—nor does it recommend one framework over another. The rationale for choosing among approaches comes from the drivers themselves: legal obligation, investor information needs, and stakeholder impact each point to different frameworks.
The concrete discipline that makes this real is an annual review of ESG performance metrics and alignment with chosen reporting frameworks by the board. That yearly checkpoint is what converts a fragmented set of disclosure demands into a governed strategy: directors can verify that mandatory scopes such as CSRD applicability and SEC climate rules are covered, that voluntary standards are serving their intended audiences, and that the reporting effort is producing its intended outcomes in reputation, risk management, and investor confidence.